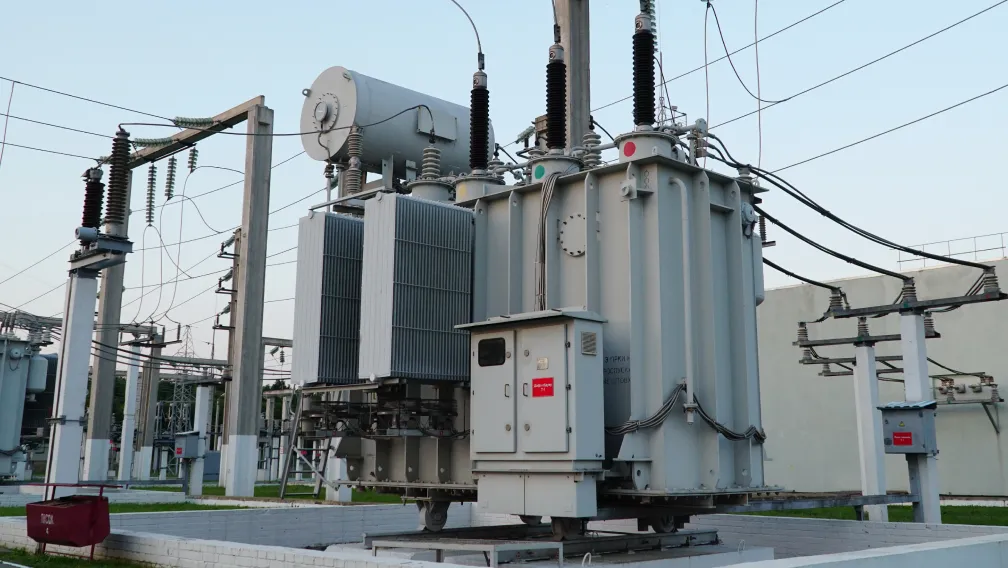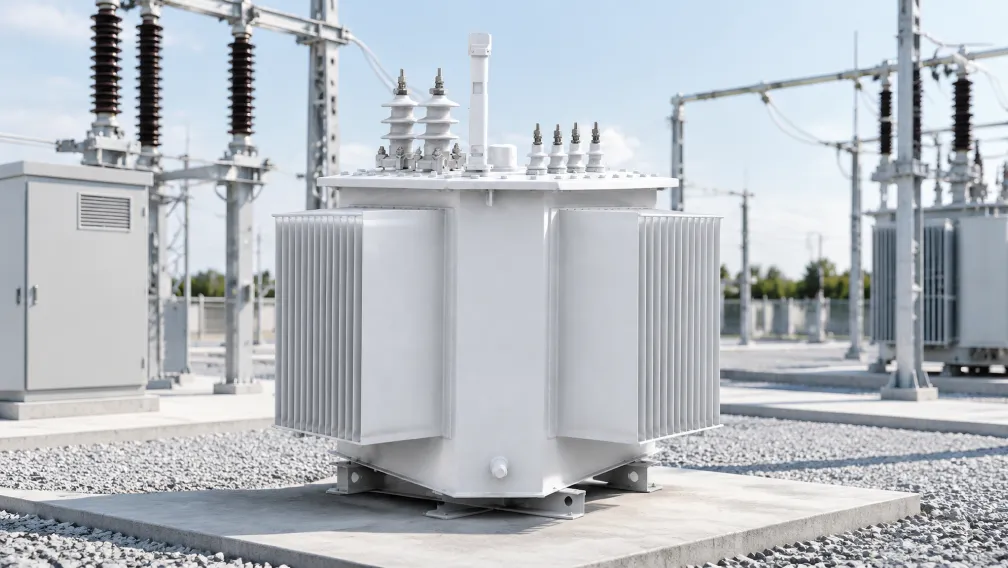


Between 16 October and 3 November 2026, the four largest Western suppliers of grid and electrical distribution equipment reported third-quarter results, and every one of them posted record order books. Schneider Electric delivered record quarterly revenue of €11.46 billion, ABB reported record group orders approaching $12 billion, GE Vernova nearly doubled its quarterly orders to $29.3 billion while signing a $9 billion acquisition of component specialist Trench Group, and Eaton pushed its electrical backlog past $20 billion with data center orders up 101 percent on a rolling basis. Read together, the four reports confirm that the grid equipment upcycle has moved from a recovery story into a structural capacity race, with direct consequences for lead times, component supply, and procurement strategy through the end of the decade.
Schneider Electric: Record Revenue and a Raised Target
Schneider Electric opened the season on 16 October with third-quarter revenue of €11.46 billion, up 16.9 percent organically against analyst expectations of 13.8 percent. Energy Management, the segment housing the group's medium voltage switchgear and distribution portfolio, grew 18.8 percent organically to €9.62 billion. Chief executive Olivier Blum told investors that data center demand grew at a triple-digit rate in the quarter and is providing visibility into 2027 and 2028. Growth was geographically broad, with China and East Asia up 26.1 percent and North America up 19.9 percent. The company raised its full-year 2026 financial target on the strength of the quarter and reported another record order backlog.
ABB: Record Group Orders, Electrification Book-to-Bill at 1.39
ABB followed on 20 October with record group orders of approximately $12 billion, up 28 percent on a comparable basis, and a record group backlog of $30 billion. The Electrification business area, which covers switchgear, distribution, and installation products, grew orders by 58 percent to more than $7 billion at a book-to-bill ratio of 1.39, lifting its backlog 59 percent to $13.7 billion. Operational EBITDA margin for the division reached a record 24.9 percent. A book-to-bill materially above 1.0 at this scale means the order book is growing faster than factories can ship, which is the precise mechanism by which lead times extend.
GE Vernova: Orders Up 96 Percent and a $9 Billion Component Acquisition
GE Vernova's 28 October report was the most aggressive of the season. Quarterly orders reached $29.3 billion, up 96 percent year-on-year at a book-to-bill above 2.0, lifting total backlog from $176 billion to approximately $197 billion. Equipment backlog alone rose to $104 billion, up 92 percent year-on-year. Within the Electrification segment, equipment backlog reached $42 billion, up 60 percent, with particular strength in substations, switchgear, and transformers; data center orders across the group have now passed $6 billion year-to-date. Management also disclosed that $900 million of U.S. transformer orders booked this year will be fulfilled by the group's global factories, a detail that underlines how much North American demand is being met from overseas capacity.
The strategically significant announcement was the $9 billion acquisition of Trench Group, a manufacturer of high-voltage bushings, instrument transformers, and coils. On the earnings call, CEO Scott Strazik quantified the logic: bushings typically represent 5 to 8 percent of a transformer's bill of materials, and across bushings, coils, and instrument transformers Trench content approaches 10 percent of the bill of materials on large HVDC orders. With high-voltage bushings quoted at lead times of roughly 130 weeks industry-wide, the acquisition is a direct vertical integration into the component bottleneck that constrains every transformer manufacturer. Trench brings approximately $5 billion in combined backlog and framework agreements, and the deal is expected to close in late 2027.
Eaton: Data Center Orders Double, Backlog Past $20 Billion
Eaton closed the reporting window on 3 November. Combined electrical segment orders grew 43 percent on a rolling twelve-month basis, and the electrical backlog reached a record above $20 billion, up 46 percent year-on-year. Electrical Americas posted record quarterly orders exceeding $5 billion with segment margins of 29.8 percent. Data center revenue grew 65 percent with orders up 101 percent, the ninth consecutive quarter above 35 percent growth. CEO Paulo Ruiz noted that announced data center projects now total 366 GW against roughly 50 GW of installed capacity, and emphasized that demand is broadening well beyond hyperscalers: utility orders grew around 20 percent, residential 25 percent, and machine OEM orders 55 percent. The company raised full-year guidance for the third time in 2026 and reported that 18 of its 25 capacity expansion projects are now complete.
Q3 2026 at a Glance
| Company | Report date | Key Q3 2026 figures |
| Schneider Electric | 16 Oct | Record revenue €11.46B, +16.9% organic; triple-digit data center growth; 2026 target raised |
| ABB | 20 Oct | Record group orders ~$12B (+28%); Electrification orders +58%, backlog $13.7B (+59%) |
| GE Vernova | 28 Oct | Orders $29.3B (+96%); backlog ~$197B; Electrification equipment backlog $42B (+60%); $9B Trench acquisition |
| Eaton | 3 Nov | Electrical orders +43% (12-mo); record electrical backlog >$20B (+46%); data center orders +101% |
What the Numbers Mean for Equipment Buyers
For utilities, EPC contractors, and industrial buyers, the practical reading of these four reports is straightforward. When every major supplier simultaneously runs book-to-bill ratios between 1.2 and 2.0, factory slots for 2027 and 2028 delivery are being allocated now, and slot reservations increasingly require down payments, as GE Vernova's working capital disclosures confirm. Component-level consolidation, exemplified by the Trench acquisition, will tighten third-party access to bushings and specialty coils. Buyers should treat equipment sourcing as a critical-path design task: qualify multiple suppliers including export-qualified manufacturers, reserve production capacity before finalizing secondary design, and negotiate escalation clauses against published indices. Projects that wait for order books to normalize will be competing for capacity against a 366 GW data center pipeline and a utility sector that is itself ordering at record rates.
Implications for the Wider Supply Chain
Record backlogs at the majors ripple outward in two directions. Upstream, demand for grain-oriented electrical steel, copper, bushings, tap changers, and cast resin components will remain allocation-managed through at least 2028, keeping input pricing firm. Downstream, buyers priced out of the majors' order books are qualifying second-tier and export manufacturers at an accelerating rate; GE Vernova's decision to fill $900 million of U.S. transformer orders from its global factories illustrates that even the largest domestic players now route North American demand through international capacity. For overseas manufacturers with IEC type-tested switchgear, transformers, and compact substations, the qualification window opened by this capacity gap is the defining commercial opportunity of the current cycle.
What to Watch Through Year-End
Three developments in the coming weeks will fill out the picture. Siemens Energy reports full-year results in mid-November, completing the set of major supplier disclosures; its grid technologies division has been running at comparable book-to-bill levels all year. GE Vernova noted that the fourth quarter is seasonally its largest for orders, and management expects the Electrification backlog to grow more in Q4 than it did in Q3, which would push equipment order coverage further into 2029 delivery windows. Finally, regulatory milestones, including the approval process for the Trench acquisition and pending Section 232 tariff decisions affecting electrical steel and transformer imports, will determine how much of the announced North American capacity expansion actually arrives on schedule. Buyers with 2028 energization dates should treat the next two quarters as the last low-competition window for factory slot reservations.
Conclusion
The October-November 2026 earnings season settled any remaining debate about the durability of grid equipment demand. Four record order books, a $9 billion bet on component supply, and broadening demand across utilities, industry, and data centers describe a market where capacity, not demand, will set the pace of electrification for years. Procurement organizations that adapt their sequencing and supplier qualification to this reality will protect their project schedules; those that treat it as a passing spike will fund their competitors' expansion instead.
Elecstellar manufactures medium and low voltage switchgear, power and distribution transformers, and compact substations for export markets, with IEC type test documentation and production slots currently available for 2027 delivery programs. To discuss capacity reservation or request type test reports, contact our export team.
-

STELLAR
Switchgear & Power Transformer ManufacturerSTELLAR designs and manufactures switchgear, transformers, and complete power distribution equipment from our China facility, serving utilities, contractors, and distributors in 50+ countries. Every technical article on this site is reviewed by our in-house engineers to ensure accuracy against IEC standards and real project practice.